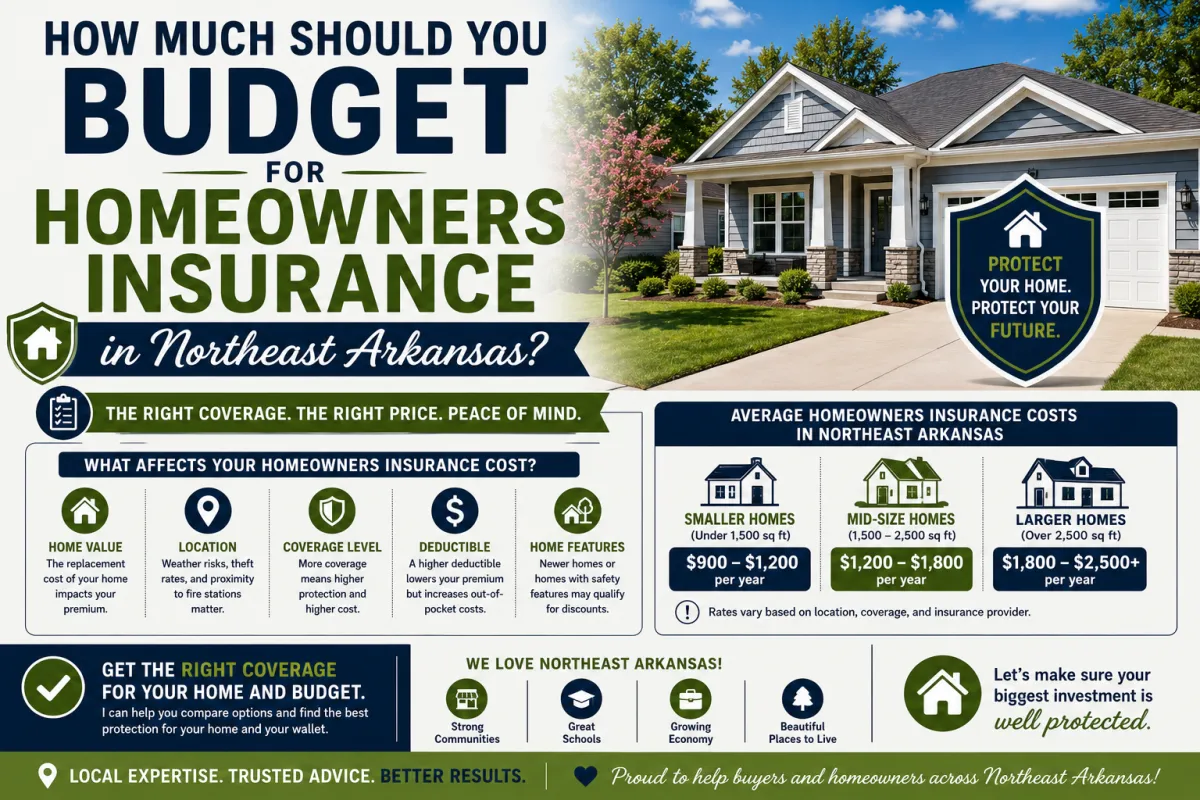
How Much Should You Budget for Homeowners Insurance in Northeast Arkansas?
How Much Should You Budget for Homeowners Insurance in Northeast Arkansas?
Quick answer: There is no single homeowners insurance price that applies to every home in Northeast Arkansas, and Arkansas premiums run meaningfully above the national average, multiple industry sources put Arkansas roughly 45-50% higher than the U.S. average, largely due to tornado and hail risk. Premiums depend on the home's location, age, construction, roof, coverage, deductible, claims history, and other factors. Buyers should get an insurance quote for the specific property before finalizing their home-buying budget.
Homeowners insurance is one of those expenses buyers often think about after they find a house.
It should be part of the conversation much earlier.
You can find a home that fits your mortgage budget perfectly and then discover that insurance costs more than expected, and in Arkansas, that gap tends to be larger than in many other states. According to ValuePenguin's 2026 analysis, the average cost of homeowners insurance in Arkansas runs about 48% higher than the national average, driven in large part by the state's frequency of severe weather. That is why the purchase price is only one part of determining whether a home is affordable.
What Determines the Cost of Homeowners Insurance?
Insurance companies consider many factors. These can include:
- Location
- Age of the home
- Roof age
- Construction materials
- Heating and cooling systems
- Electrical systems
- Plumbing
- Replacement cost
- Coverage limits
- Deductible
- Claims history
- Certain property characteristics
Two homes with the same purchase price can have different insurance premiums.
Why Is Arkansas Homeowners Insurance More Expensive Than the National Average?
Weather risk is the biggest driver. Arkansas experiences frequent severe storm activity, tornadoes, hail, and high winds, which pushes claims frequency, and therefore premiums, higher than in many other states. This is worth knowing going in: it isn't a sign something is wrong with a particular property, it's a statewide pattern buyers should budget for.
Why Does the Roof Matter So Much?
The roof is one of the most important components of a home from an insurance perspective.
A newer roof may be easier to insure than an older roof, depending on the insurer and policy. If you are considering an older Jonesboro, Paragould, or Brookland home, ask: How old is the roof? Then find out what the insurance company says about it.
Do not assume a roof that looks fine from the ground will automatically be acceptable to every insurer.
Does the Location of a Home Affect Insurance?
Yes.
Insurance companies consider location when evaluating risk. Factors may include weather exposure, claims patterns, emergency services, and other characteristics of the property's location.
This is another reason you should obtain an insurance quote for the specific address rather than using a generic estimate.
What Coverage Should Buyers Understand Before Choosing a Policy?
| Coverage Type | What It Covers |
|---|---|
| Dwelling coverage | Cost to rebuild the physical structure of the home after a covered loss |
| Personal property | Replacement of belongings, furniture, electronics, clothing, after a covered loss |
| Liability coverage | Legal and medical costs if someone is injured on the property or you're found liable for damage |
| Loss of use / additional living expenses | Temporary housing and related costs if the home is uninhabitable after a covered loss |
Should You Shop Around for Homeowners Insurance?
Yes.
Insurance pricing can vary among companies. Getting multiple quotes can help you understand the range of available premiums and coverage.
But don't compare only the price. Compare: coverage limits, deductibles, exclusions, replacement cost provisions, liability coverage, and claims service.
The cheapest policy isn't necessarily the best value.
What Happens If a Home Has an Older Roof?
This is something to investigate before making an offer.
An older roof may not automatically make a home uninsurable. However, an insurance company may have specific requirements regarding roof condition or age.
If you're considering an older property, contact your insurance agent early. That way you are not discovering a problem at the last minute.
Should Insurance Be Included in Your Monthly Housing Budget?
Yes.
Your monthly housing cost may include: mortgage principal, mortgage interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues.
You may also need to budget for maintenance and utilities. Thinking about all of these expenses before buying gives you a more realistic picture of affordability.
What About Flood Insurance?
Standard homeowners insurance generally does not cover flooding.
If a property is in or near an area where flood risk is a concern, ask your insurance professional whether separate flood insurance is appropriate. Don't assume that being outside a high-risk flood zone means there is zero risk.
Your lender, insurance agent, and other professionals can help you understand the property's specific situation.
What Should You Do Before Making an Offer?
Once you find a home you like, get an insurance quote as early as practical.
Give the insurance agent accurate information about: the property address, year built, square footage, roof age, HVAC, construction, and previous insurance information if available.
The more accurate the information, the more useful the quote.
Frequently Asked Questions
How much does homeowners insurance cost in Jonesboro?
There is no universal price. Premiums vary by property and coverage, and Arkansas as a whole tends to run well above the national average due to storm risk. The best way to determine the likely cost is to obtain a quote for the specific home.
Does the age of a home affect insurance?
It can. Older homes may have older roofs, electrical systems, plumbing, or other components that can affect insurance eligibility and premiums.
Does a new roof lower homeowners insurance?
It may, depending on the insurer and the policy. A newer roof can reduce certain risks, but buyers should ask the insurance company rather than assuming a specific discount.
Do I need flood insurance?
It depends on the property and your risk. Standard homeowners insurance generally does not cover flooding, so buyers should discuss flood risk and coverage with their insurance professional.
Should I get an insurance quote before buying?
Yes. Getting a quote early can help you determine the home's true monthly ownership cost, especially in a state where premiums run above the national average.
Can two similar homes have different insurance premiums?
Yes. Location, construction, roof age, claims history, coverage, deductibles, and other factors can produce different premiums.
What is the best homeowners insurance company?
There is no single company that is best for every homeowner. Compare coverage, exclusions, deductibles, service, and premiums for your specific property.
Final Thoughts
Homeowners insurance isn't the most a big step part of buying a house. But it is important, and in Arkansas, it's a bigger line item than buyers moving from many other states may expect.
Before you fall in love with a property, understand what it will cost to own. Get the mortgage numbers. Estimate taxes. Get an insurance quote. Think about maintenance. Then look at the entire monthly picture.
A home is a long-term financial commitment. The more you understand before closing, the fewer surprises you're likely to encounter afterward.
Jonesboro, AR Property Taxes: What Homebuyers Should Know
What to Know Before Buying an Older Home in Jonesboro, AR
Selina Reithemeyer
Executive Broker, Image Realty
3501 Stonegate Dr, Suite D, Paragould, AR 72450
870-219-4890
